
EMI stands for Equated Monthly Installment. It is the amount scheduled to be paid toward a loan each month, including both principal and interest. The amount of money that you have to pay every month for your loan—this includes both the amount of principal that you have to pay back and the interest that is charged on your outstanding loan balance.

EMI Calculator
Estimate monthly EMI, total interest, and total payment on a loan.
When it comes to loans, whether it’s a mortgage, car, personal loan, or anything else, the defining factor is not just the interest rate, but the actual monthly cost of the loan. A loan EMI calculator helps you estimate your Equated Monthly Installment using three key inputs: loan amount, interest rate, and loan tenure. It will also be able to provide you with the total amount of interest you would pay throughout the life of your loan and the total sum of the loan repayments, so that you can compare the options available for your loan without relying on assumptions. The formula does not change with the size of the borrowing, so it works as a bike EMI calculator for a two-wheeler just as well as it does for a house — a bike loan EMI calculator is the same tool with smaller numbers in it.
How to use the EMI Calculator
- Type in the loan amount you are thinking about.
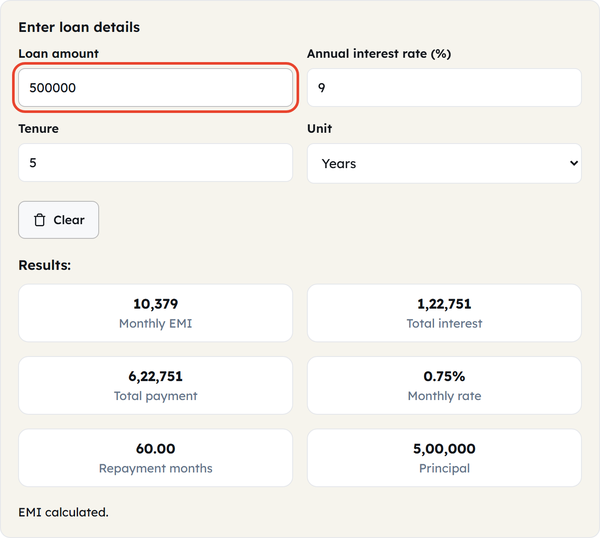
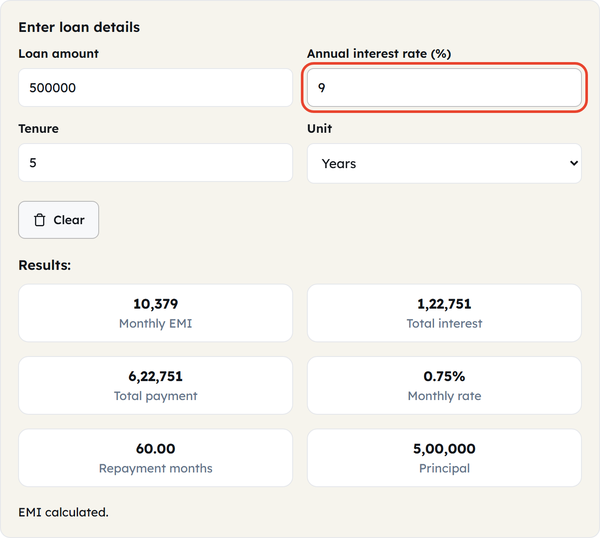
- Enter the annual interest rate quoted by the lender.
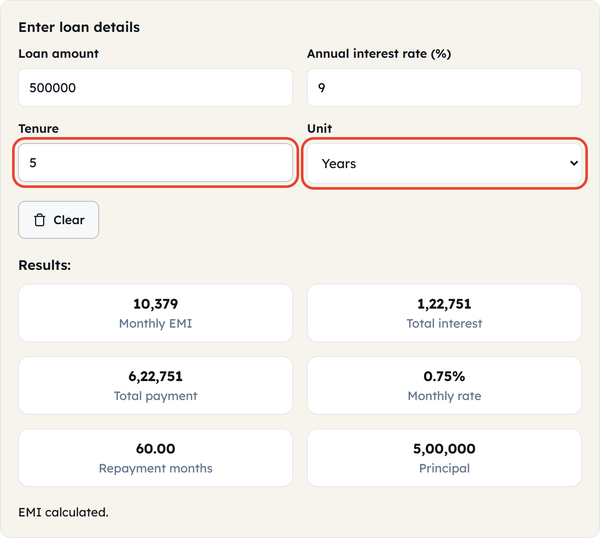
- Enter the loan tenure in years or months, depending on the calculator’s input format.
- Read the result: It shows you your monthly EMI, the total interest paid over the entire period, and the total repayment amount (principal + interest).
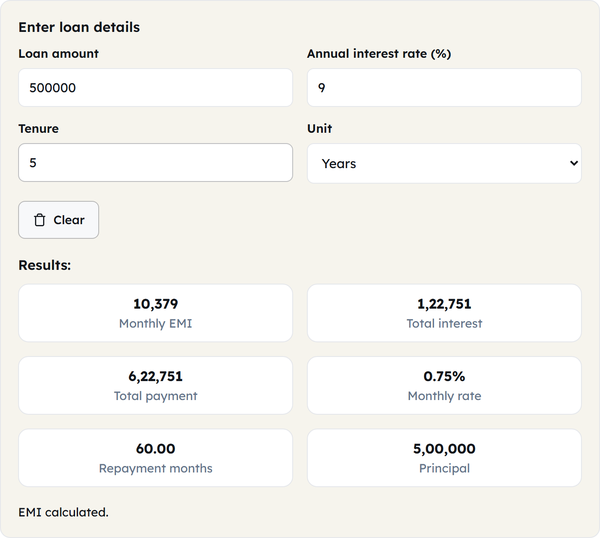
- Any input will update the result in real time, allowing you to see how different loan amounts, rates, or tenures compare.
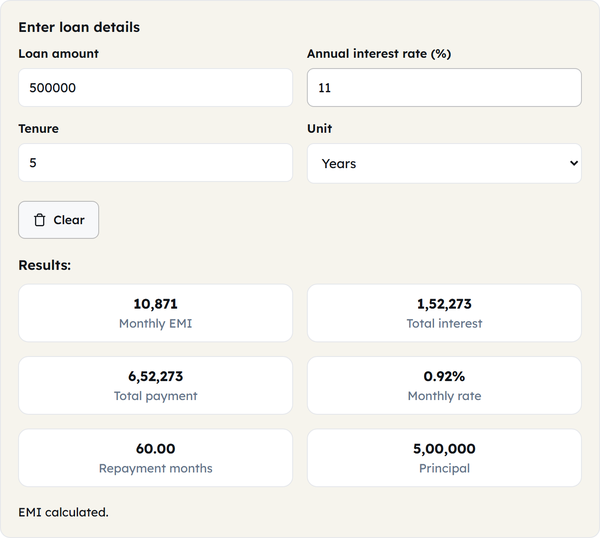
- Click Clear to reset the fields and start a new calculation.
What is EMI and how is it calculated?
Equated Monthly Installment (EMI) is a fixed amount paid each month that includes the principal of the loan as well as the interest on the remaining balance. The formula for calculating it is:
EMI = [P × R × (1+R)^N] / [(1+R)^N − 1]
Where:
P = the loan principal (the amount borrowed)
R = the monthly interest rate (annual rate ÷ 12 ÷ 100)
N = the number of monthly installments (tenure in months)
Worked example: for a loan of ₹10,00,000 at an annual interest rate of 7.2%, repaid over 120 months (10 years), the monthly rate R = 7.2 ÷ 12 ÷ 100 = 0.006. Using the formula, the EMI comes out to be approximately ₹11,700 per month, the total repayment for the loan term is approximately ₹14 lakh and the total interest paid during the loan period is approximately ₹4 lakh. It’s really very tedious to do by hand — that’s the point of a calculator, right?
A thing many people don’t realize: the EMI amount remains the same each month but the interest and principal components of the EMI are different each month. The first few months are quite high in interest because interest is applied to the balance outstanding and that is highest at the beginning. Although the total EMI remains the same, the interest portion generally decreases over time as the outstanding balance falls, while the principal portion increases. Remember that processing fees and other lender charges are generally separate from the interest used in the EMI formula. Consider them when comparing the total cost of different loans.
When you’d use this
Before you take any loan, comparing loan offers from different lenders, checking how varying the loan tenure affects your monthly EMIs and interest cost, estimating affordability before you go on a loan hunt for a home, car, or any large purchase, and checking a lender’s quoted EMI with an independent calculation.
Dos and Don’ts
Do:
- When comparing the length of time, watch total interest paid rather than the monthly EMI.
- Since the processing fees/ charges that your lender get listed separately from the interest rate is not a part of the EMI formula itself, then use the actual interest rate quoted by your lender.
- Calculate using various tenures to understand the true cost-benefit of paying less each month or less over the term of the loan.
Don’t:
- Any lower EMI automatically translates to a cheaper loan – longer duration means lower EMI, but it also means that more interest will be paid in total.
- This calculator is a reassuring indicator of a loan offer you can be sure of — real terms will depend on the lender’s evaluation of your income, credit history, and more.
- This calculator provides an estimate for planning purposes and is not financial advice. Check the final loan terms, fees, and eligibility requirements directly with your lender.
Good to know
There are three factors that affect your EMI: loan amount, interest rate and tenure — and it’s important to understand how each of these moves the number. If the loan amount is higher or the interest rate is higher, the EMI will be higher. Choosing a longer tenure can reduce the monthly EMI, but it generally increases the total interest paid over the life of the loan. Your affordable EMI depends on factors such as income, existing debt, expenses, interest rate, loan tenure, and the lender’s eligibility criteria. Running an EMI calculator online before you walk into a branch means you arrive with your own numbers rather than only the lender’s. This calculator provides a planning estimate; it is not financial advice and actual loan terms, fees and eligibility will vary with the lender. All the calculations on this page are performed in your own browser — no information is sent or stored.
FAQ: EMI Calculator Questions
What is EMI?
What is the EMI formula?
EMI = [P × R × (1 + R)ᴺ] ÷ [(1 + R)ᴺ − 1], where, P is the principal amount of the loan, R is the rate of interest per month, and N is the number of installments per month.
Why is more interest paid in the early months of a loan?
Interest is generally calculated based on the outstanding principal balance. At the beginning of an amortizing loan, that balance is highest, so a larger portion of the EMI goes toward interest. As the principal decreases, the interest portion generally falls and more of the EMI goes toward principal.
What factors affect my EMI amount?
The three key factors are the loan amount, the interest rate and the loan tenure. A higher interest rate and greater loan amount would mean that the EMI would also be higher, but a longer loan tenure would result in the EMI becoming lower, but the interest paid on the loan would be higher over the period.
Does a longer loan tenure always save money?
No. The longer you have to pay off the loan, the lower the EMI, but the more interest you pay over the life of the loan, as it accruals for a longer period. Shorter tenures will yield higher EMIs and a lesser amount of total interest paid.
Are the numbers from this calculator stored or sent anywhere?
No. All the calculations are performed in your browser and no numbers are sent or stored.
Related Tools
Password Strength
Score password strength and spot weak patterns.
- 100% Free
- Customizable
- Download
- Unlimited
Percentage Calculator
Calculate percentages, increases, and decreases.
- 100% Free
- Customizable
- Download
- Unlimited
Age Calculator
Find exact age in years, months, and days.
- 100% Free
- Customizable
- Download
- Unlimited
Date Difference
Measure days between any two dates.
- 100% Free
- Customizable
- Download
- Unlimited
BMI Calculator
Compute body mass index from height and weight.
- 100% Free
- Customizable
- Download
- Unlimited
Discount Calculator
Find sale prices and savings in seconds.
- 100% Free
- Customizable
- Download
- Unlimited